The Black Hole of Middle Relief
Modern baseball has a massive, undeniable math problem. The quantitative evolution of MLB effectively broke traditional moneyline betting models years ago. Today’s managers operate purely on biomechanical thresholds. They will ruthlessly pull aces after five frames to preserve elbow ligaments and optimize late-game matchups. Let’s be real, paying a steep -150 premium for a starting pitcher duel—only to watch some fatigued setup man blow the lead in the seventh—is a phenomenal way to torch a bankroll. Professional gamblers know this reality intimately. A highly specific antidote exists for those willing to exploit isolated phases of the game.
This specific derivative market elegantly removes late-game variance entirely. Your absolute risk profile rests squarely on the shoulders of the starting pitcher.
Analytics, Leverage, and the Volatility Tax
We have to examine the mathematical decay that occurs the moment a starter leaves the mound. Relief pitchers undoubtedly possess elite velocity. Their game-to-game stability, however, is statistically atrocious. Year-to-year correlation for a starter’s strikeout rate hovers reliably around 0.82; that identical metric plummets to 0.675 for bullpen arms. Volatile sequencing stats tell an even scarier story. The Home Run to Fly Ball ratio drops from a somewhat projectable 0.29 for starters to a completely chaotic 0.07 for relievers.
The math gets ugly late in games. Picture the bases loaded, two away in the eighth; that specific scenario carries a monstrous 2.667 situational leverage score. Your meticulously crafted algorithm? Gone. A single spiked curveball in the dirt torches the whole thing.
The Third-Time Trap and Mid-Summer Dead Arms
Let’s look at the absolute physical carnage we saw across modern bullpens this year. The 162-game gauntlet inevitably turns middle relievers into dust by late summer. Look closer at the final stretch, and the localized fatigue metrics are glaring. Chicago’s White Sox relief corps threw over 3,200 pitches after July 1st. This massive workload directly caused their strikeout-minus-walk rate to collapse to an unsustainable 10.9%. Over in the National League, overworked Dodgers relievers posted a catastrophic 12% walk rate in the second half.
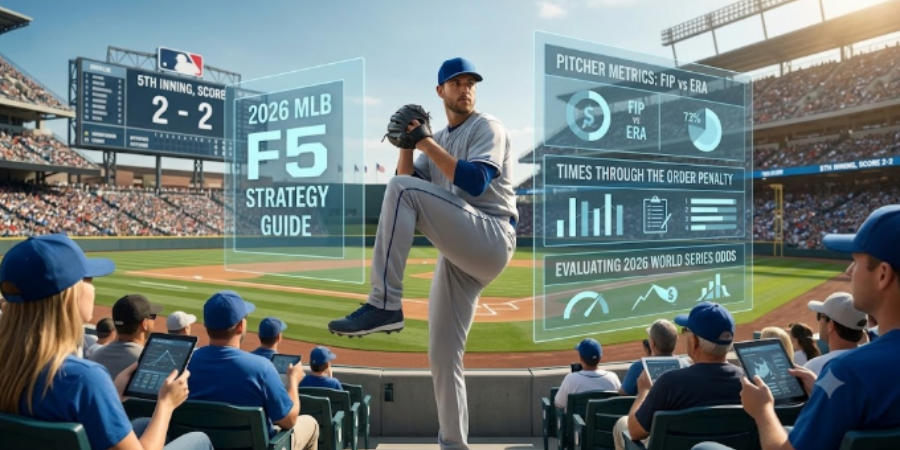
Analysts attempting to price this localized fatigue into a full-game moneyline introduce an unacceptable margin of error. Starting pitchers provide a mathematical sanctuary from this chaos, at least until they collide with the Times Through the Order Penalty (TTOP). Big league bats don’t stay fooled for long. They figure out the release point. They start recognizing the tunneling action. By the time a batter gets a second look at a starter, his Weighted On-Base Average (wOBA) jumps by roughly nine points. Metrics completely implode by the third pass, which typically occurs right in the late fifth or early sixth inning. Bettors cash F5 tickets exactly before this biomechanical danger zone materializes.
Run Expectancy and Front-Loaded Scoreboards
Recreational gamblers consistently commit a fatal structural error when evaluating totals. A widespread public assumption dictates that the first five innings represent a simple mathematical half of a game’s total offensive output. Sabermetrics proves otherwise. Baseball scoring heavily concentrates in the early frames because managers specifically stack their elite OBP and slugging threats at the top of the lineup. These high-caliber hitters are strictly guaranteed to see the plate two or three times before the fifth inning concludes.
Early command issues for starting pitchers further compounds this reality. The first inning routinely operates as an incredibly volatile scoring environment. Minnesota capitalized on this exact phenomenon to post a 34.57% Yes Run First Inning (YRFI) rate this year. Historical run expectancy matrices (RE24) confirm that approximately 54.1% of all projected scoring takes place within this truncated first-half window. Recreational players love to take an 8.5 full-game total and just chop it in half. The math absolutely punishes that lazy shortcut. Sharp syndicates aren’t even glancing at the full-game number when a loaded top-of-the-order gets a matchup against a weak right-hander. They pivot instantly to F5 team totals to capture this front-loaded volume.
FIP, Microclimates, and Synthetic Latency
Actual statistical edges mean nothing without proper market execution. Sportsbooks relentlessly guard their primary full game moneylines with automated trading algorithms. Those primary numbers adjust in milliseconds when sudden lineup scratches occur. Derivative markets—specifically F5 moneylines and run lines—do not receive that same instantaneous respect. Bookmakers rely on synthetic pricing formulas to adjust these secondary numbers, creating a beautiful inefficiency known as derivative latency. Savvy operators utilize odds screens to snipe these stale prices before the bookman manually intervenes.
We must strip away the noise to find a pitcher’s true baseline. Earned Run Average (ERA) belongs in the trash for predictive modeling. It bakes in too much garbage—defensive errors, terrible shifts, random batted-ball luck. The guys moving the market look strictly at Fielding Independent Pitching (FIP) and Expected FIP (xFIP). They want to isolate what the pitcher controls: Ks, walks, and bombs. See a starter out there with a hideous 4.50 ERA but a rock-solid 3.20 FIP? That is your golden ticket. Retail money panics and fades the ugly ERA, handing you massive +EV on the F5 moneyline.
Mother Nature always gets the final say. Altitude adjustments in Denver or wind vectors at Wrigley literally change the physics of a baseball in flight. A 15-mph gale blowing straight in from the center? That turns a scary 5.5 F5 Total into an absolute hammer spot for the Under. Mastery of these localized micro-edges is how you compound daily bankrolls. And here is the real secret: that steady cash flow funds your bigger October swings. An accurate grade on a team’s true starting rotation baseline is exactly how you uncover the mispriced 2026 World Series odds before the global market catches up.
Run Line Mechanics and Fractional Survival
Your survival out here completely depends on understanding the counter structure. You must explicitly target two-way F5 moneylines at the betting window. Three-way markets deceptively grade a tie as a complete loss. This is disastrous given the high frequency of 2-2 or 3-3 deadlocks in the fifth inning. The two-way market refunds your stake on a push, perfectly insulating your capital from early-game noise. Amateurs constantly bleed money by misclicking the three-way line and losing a wager that should have resulted in a harmless refund.
The F5 run line offers another potent derivative weapon for sharp bettors. Standard full-game run lines force bettors to lay -1.5 runs, a dangerous proposition if an underdog bullpen randomly shuts down late scoring. The F5 variant typically rests at a much safer -0.5. Gamblers backing a heavy favorite merely require a one-run lead at the halfway mark. An underdog ticket at +0.5 provides incredible mathematical cover, cashing out smoothly even if the game is deadlocked.
Fractional Kelly criterion sizing takes this risk mitigation even further. Elite betting syndicates outright refuse to overexpose themselves. They strictly wager 1% to 3% of their total bankroll on any single F5 edge. Variance remains a vicious predator, even inside a truncated five-inning window. Sudden rain delays, unexpected early platoon substitutions, and rogue blisters can derail the most beautifully calculated xFIP projection.
The reality is brutal for the uneducated bettor. Success in today’s game has zero to do with praying an exhausted closer finds the strike zone in the ninth. The real edge is all about isolating a starter’s true talent, avoiding the late-game circus entirely, and letting the raw math do the heavy lifting.